Most of us will need help with daily life at some point as we age. That might mean a caregiver at home, adult day care, or even a move to assisted living or a nursing home.
Paying for that care is one of the biggest worries we hear from Maryland families. Long-term care insurance is one option to cover the expense. The market has changed, though. Premiums have risen, and many buyers now choose hybrid policies that pair care coverage with life insurance.
This guide explains how long-term care insurance works and how to decide if it fits your plan. It draws on research from AARP and federal agencies, plus our experience helping Maryland families since 1997.
Key takeaways
- Long-term care insurance pays for help with everyday activities at home, in assisted living, or in a nursing home.
- Ongoing long-term care is not covered by Medicare, and Medicaid helps only after you’ve spent most of your savings.
- Hybrid policies combine care coverage with life insurance. They cost more, but they pay out either way.
- Buying in your 50s usually means lower premiums and a better chance of approval.
- Maryland Partnership policies let you keep more of your assets if you later need Medicaid.
What is long-term care insurance?
Long-term care insurance is a policy that pays for help when you can no longer manage everyday tasks on your own. It covers care that health insurance and Medicare usually leave out.
Most policies pay for some mix of in-home care, assisted living, nursing home care, adult day care, and respite care for family caregivers.
A traditional policy works like car or home insurance. You pay a premium each year, and the policy pays benefits if you need care. If you never need care, the insurer keeps the premiums. AARP reports that about 6.1 million Americans had traditional coverage in 2022.
How likely are you to need long-term care?
More likely than most people expect. A study from the U.S. Department of Health and Human Services (HHS) reports that 56% of individuals turning 65 will need significant long-term care later in life. About 14% will need more than two years of paid care.
HHS puts the average cost of that care at $120,900. Your cost will depend on how long you need help, how much help you need, and where you live.
Does Medicare pay for long-term care?
No. Traditional Medicare does not cover long-term care. It pays for short-term skilled care after a hospital stay, but not for ongoing help with daily living.
Many people don’t know this. A KFF survey found that nearly half of adults 65 and older wrongly believe Medicare would pay for a long nursing home stay. In the same survey, 90% said a year of nursing home care would be impossible or very hard for their family to afford.
Medicaid covers long-term care only for people with low income and few assets, usually after they spend down their savings. The U.S. Department of Veterans Affairs is an avenue veterans may use for additional home and community care.
That leaves most families paying out of pocket. Financial adviser Ryan Graham of Altfest Personal Wealth Management told AARP, “Everyone needs a long-term care plan.” He added that not everyone needs a policy.
What is a hybrid long-term care policy?
A hybrid policy combines long-term care coverage with life insurance or an annuity. The Congressional Research Service reports that most long-term care policies sold since 2010 are hybrids.
Many hybrid policies work like this:
- You pay one lump sum, or a fixed amount spread over a set number of years. The price can’t rise later.
- If you need care, the policy pays benefits. If you never do, your heirs receive a life insurance payout.
- Using care benefits reduces the death benefit or uses it up.
- Some policies refund your payment if you cancel in the first few years.
The appeal is simple. You get something back whether or not you ever need care. Christine Benz of Morningstar told AARP this eases a common fear of paying for years and never using the coverage.
That guarantee costs more. Hybrid policies are pricier than traditional ones, and the life insurance payout is often modest. AARP’s guide to hybrid long-term care insurance compares the two types.
How does a long-term care insurance policy pay benefits?
Every policy has rules about when benefits start and how much they pay. Check these terms before you buy.
Benefit triggers. Most policies pay once you can’t do a set number of activities of daily living alone, such as bathing, dressing, eating, or using the toilet. A cognitive impairment like dementia also qualifies.
Elimination period. The waiting period before benefits begin. Ninety days is most common. A shorter wait raises your premium, and a longer wait lowers it.
Benefit limits. Policies cap what they pay per day or month. They also set a lifetime maximum or a fixed number of years.
Inflation protection. Benefits that grow each year cost more, but they keep pace with rising care costs. A policy that pays $200 a day and grows 3% a year costs more than a flat $100-a-day policy.
Exclusions. Many policies won’t pay for care related to alcoholism, drug addiction, or war injuries. Care tied to a preexisting condition may be excluded for a period after the policy starts.
Premium waiver. Once you start receiving benefits, most policies stop charging premiums.
Can long-term care insurance pay for in-home care in Maryland?
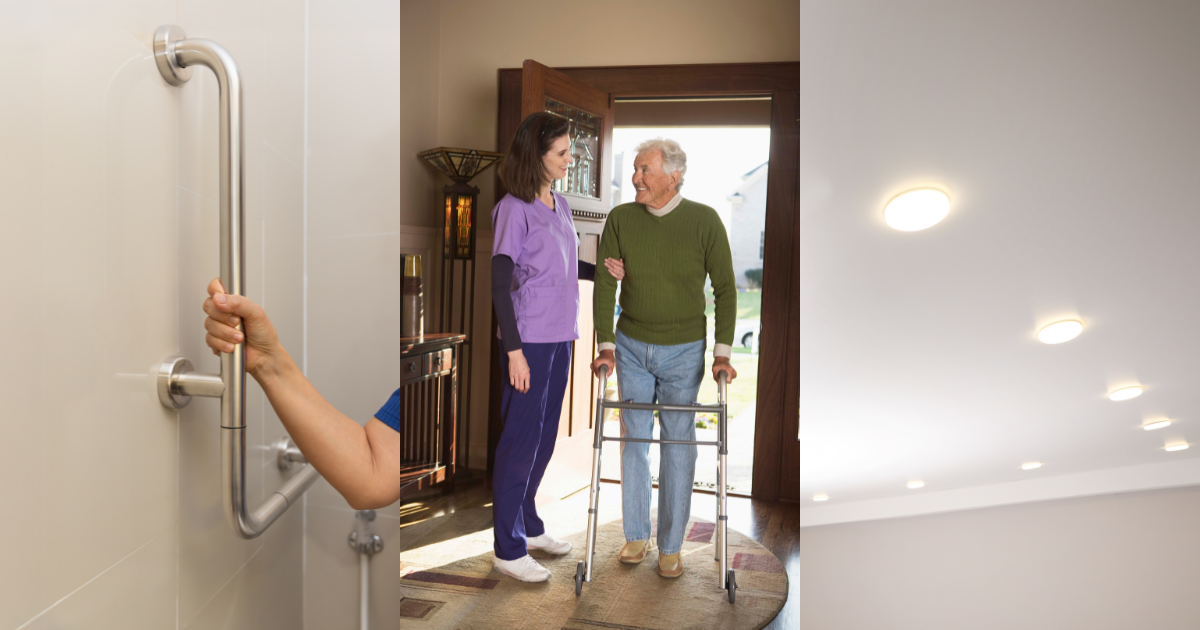
Yes. Most policies sold today cover in-home care, and that matters. Most senior adults would rather stay in their own homes as long as possible safely.
At Chesapeake Caregivers, we accept long-term care insurance and private pay. Our caregivers help with bathing, dressing, meals, mobility, and other activities of daily living. These are the same tasks most policies use to decide when benefits begin. We also provide memory care for clients living with Alzheimer’s or other forms of dementia.
If you already have a policy, we can work directly with your insurance company. Our guide on paying for in-home care in Maryland covers long-term care insurance, VA benefits, and other ways families pay for care. You can also read about our affordable home care options.
Why did long-term care insurance premiums increase?
Early policies from the 1980s covered nursing homes. Later policies added home care, assisted living, and adult day care, and some promised lifetime benefits.
Insurers misjudged the numbers. Claims ran higher, and investment returns ran lower, so many raised premiums with state regulators’ approval. Many insurers left the market. The few that still sell traditional policies offer shorter coverage periods at higher prices. Newer policies are priced to avoid a repeat.
What should you do if your premium goes up?
If your traditional policy gets a rate increase, you have two main choices.
You can pay the higher premium and keep your full benefits. This often makes sense if you can afford it and your older policy has generous terms. Or you can keep your current premium and accept smaller benefits, such as a shorter benefit period.
Think hard before you drop a policy. New coverage almost always costs more as you age. As long as you keep paying, the insurer can’t legally cancel your policy.
Should you buy long-term care insurance?
There is no single right answer. Before you decide, weigh these factors.
Your budget. According to the National Association of Insurance Commissioners (NAIC), premiums should take no more than 7% of your income. If you already struggle to pay for food, medicine, or utilities, a policy is likely not a good fit.
Your assets. According to the NAIC, insurance is most likely to pay off if you have at least $75,000 in assets, not counting your home. With less than $30,000, you may pay more in premiums than you would gain.
Other ways to pay. Some families plan to use savings, sell a second home, downsize, or take out a reverse mortgage.
Your goals for your heirs. Some people want to protect an inheritance. Others would rather spend their savings on their own care.
Your age and health. Premiums and denial rates both rise with age. If you already have memory loss or need help with self-care, you likely won’t qualify. AARP notes that many advisers now suggest shopping in your 50s.
Independent advice. Talk with an agent who sells policies from several insurers, or a financial adviser with no stake in any one company.
How can you lower the cost of a policy?
Ask about group coverage. Some employers offer group long-term care insurance. It can cost less than an individual policy, especially if you have health problems.
Apply as a couple. Couples often pay less. Many policies also offer shared care, which lets one spouse draw on the other’s benefits.
Use tax-advantaged money. You may be able to pay premiums tax-free from a health savings account (HSA). You can also exchange a life insurance policy or annuity for a long-term care policy.
Choose a Maryland Partnership policy. If you later need Medicaid, a Partnership policy lets you keep more of your assets, based on what the policy has already paid. The Maryland Insurance Administration publishes a consumer guide to the Partnership Program.
Frequently asked questions about long-term care insurance
What does long-term care insurance cover?
Most policies cover help with daily activities at home, in assisted living, or in a nursing home. Many also cover adult day care and respite care.
When should I buy long-term care insurance?
Many advisers suggest your 50s. Premiums are lower then, and you are more likely to pass the health review. Waiting until your late 60s or 70s raises the cost and the chance of being turned down.
Is long-term care insurance worth it?
The answer depends on several factors, including your income, assets, and goals. NAIC suggests it fits best when premiums stay under 7% of income, and you have at least $75,000 in assets outside your home.
Does Chesapeake Caregivers accept long-term care insurance?
Yes. Chesapeake Caregivers accepts long-term care insurance and private pay, and we can work directly with your insurer. Medicare does not cover non-medical home care.
Plan ahead for care at home
Planning early gives your family more choices later. Chesapeake Caregivers offers a free, no-obligation in-home assessment for families in Annapolis, Anne Arundel County, and Queen Anne’s County. Contact us or call 410.919.0190 to get started. Not sure if it’s time? Here are signs it could be time to consider in-home care.
Source: AARP, Understanding Long-Term Care Insurance, updated February 2024.